
Your parts supplier in Pune invoices in rupees and needs the money in a local bank account before the next production run. Your dollar wire left on Monday, and by Thursday it is still stuck with a correspondent bank.
Local bank transfer payouts to India with a stablecoin settlement layer close that gap. You fund in USDC or USD, lock a quote, and a licensed local payout partner delivers Indian rupees (INR) to the recipient’s bank account.
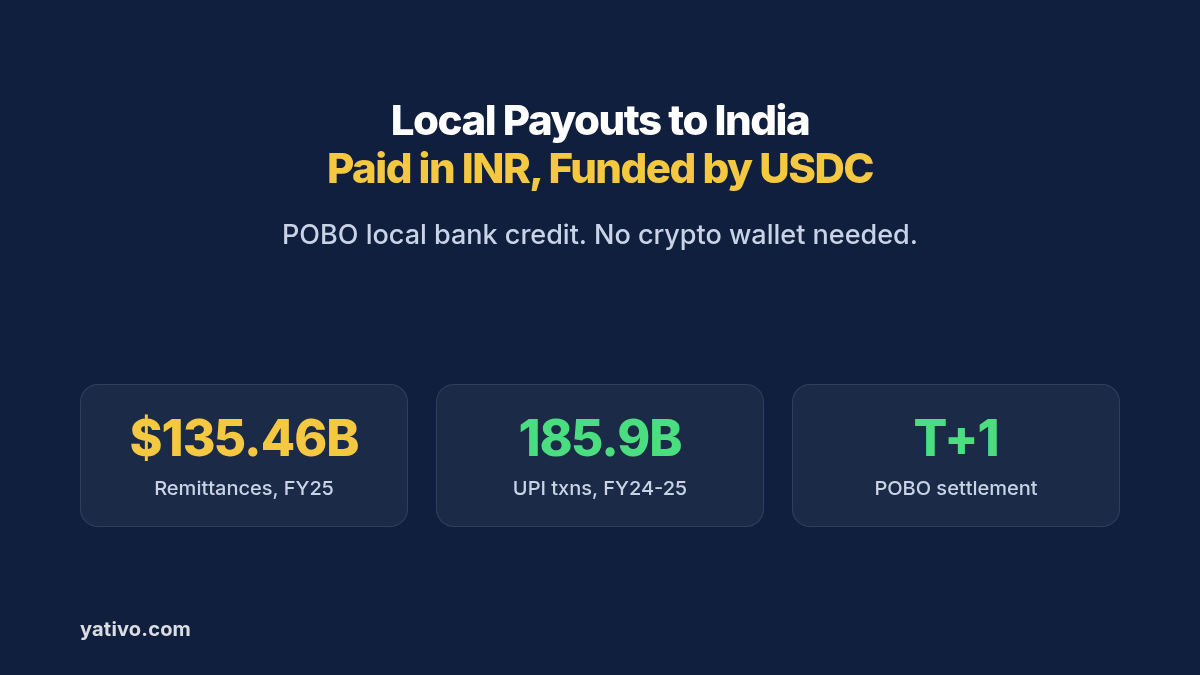
India is the world’s largest remittance destination. Diaspora remittances hit a record US$135.46 billion in FY25, according to RBI data reported by The Economic Times. Domestic rails move at massive scale: UPI alone processed about 185.9 billion transactions in FY2024-25.
This guide covers why India payouts stall, how the stablecoin-funded flow works, and which recipient details you need. It then walks through your first INR payout by dashboard and by API. One product fact up front: the active local method is POBO, so settlement is next business day (T+1), not under 30 minutes.
Why Paying Out in India Is Harder Than It Should Be
India’s domestic payment systems are among the busiest in the world. The friction sits at the border, where a foreign payment meets currency conversion, intermediary banks and incomplete beneficiary data.
Small cross-border transfers are expensive. Sending small amounts abroad costs an average of 6.36% of the amount sent, according to the World Bank. On a US$20,000 monthly contractor payroll, that average would cost about US$1,272 every month. We break down more of these costs in the hidden costs of international payments.
Inbound wires get converted on the bank’s terms. A dollar wire to a rupee account is converted at whatever rate the receiving bank sets that day. Your recipient sees the final amount only after the money lands.
Correspondent chains add days. A SWIFT payment can pass through one or more intermediary banks before it reaches Mumbai or Bengaluru. Each hop can deduct a fee and add a day.
The details have to be exact. A wrong IFSC, account number or legal name is the fastest route to a rejected payout and a week of emails.
Local Bank Transfer Payouts to India with a Stablecoin Layer: How It Works
Yativo is payment infrastructure, not a bank. We use stablecoins as the settlement layer between your balance and India. A licensed local payout partner then delivers the rupees on the ground.
- You fund your Yativo float balance with a fiat or stablecoin deposit, such as USDC.
- Yativo converts the payout value to USDC and settles it on-chain.
- A licensed local payout partner in India receives the stablecoin settlement.
- The partner converts USDC to INR and sends a domestic bank credit to the recipient’s account.
- Your recipient receives rupees in their normal bank account.
Your recipient does not need a crypto wallet. They never see or touch stablecoins. On their side, the payment looks like any domestic credit from a local sender.
The local rails can carry the volume. Besides UPI’s 185.9 billion FY2024-25 transactions, NEFT processed about 9.62 billion transactions in the same year. For more on the settlement layer, read how to receive international payments in stablecoins.
Supported Payout Rails for India
Yativo’s featured method for this guide is POBO (Local) in INR. It is the only active local bank method for India in the current catalog. Our India list also includes SWIFT for dollars and a SWIFT (POBO) option in INR. All three settle next business day (T+1).
POBO (Local) INR (featured)
POBO (Local), gateway ID 1057, pays Indian rupees into a domestic bank account on behalf of your business. It needs the Collection/Payment-on-behalf-of endorsement on your customer, so confirm that with your account executive before you build.
Required details: the fields returned by the India payout form, gateway ID 1057. Expect the holder’s legal name, IFSC and account number. For exact field names, see API documentation.
Settlement time: next business day (T+1). Do not treat this rail as an under-30-minute local payout.
Best for: suppliers, contractors, payroll recipients and marketplace sellers who bank in India and accept T+1 delivery.
SWIFT and SWIFT (POBO)
SWIFT, gateway ID 618, pays USD and settles next business day (T+1). SWIFT (POBO), gateway ID 1112, pays INR under a pay-on-behalf-of SWIFT path and also settles next business day (T+1). Availability depends on your account, so check the live list before you build.
Recipient Details to Collect Before Your First INR Payout
The India payout form in your dashboard, or the authenticated GET /beneficiary/form/show/1057 call, is the authoritative field list. Our public documentation does not publish this form yet. Collect the details below during onboarding so you can fill it without a round of emails.
- Holder type: individual or company.
- Legal name: full name as it appears on the PAN or passport, or the registered company name that matches the bank account.
- Bank account number: the rupee account that should receive the credit.
- IFSC: the 11-character Indian Financial System Code for that branch.
- ID details: any tax ID or KYC fields the form returns for individuals or companies.
Ask for a bank statement screenshot or a cancelled cheque image during onboarding. It removes most IFSC and account-number typos before the first payout.
How to Send an INR Payout via Yativo
Option 1: Dashboard (for manual payouts)
- Fund your Yativo float balance with either a fiat or a stablecoin deposit.
- Go to Transfer in your Yativo dashboard.
- Select the float wallet you are paying with, for example USD, EUR, MXN or whichever balance you funded.
- Choose the customer you are paying on behalf of. This step is necessary for fintechs that run payouts on behalf of their customers.
- Choose India as the destination country and the POBO (Local) payout method.
- Enter the recipient details the payout form asks for, such as the holder’s name, IFSC and bank account number.
- Enter the amount in USD or INR.
- Review the quote: exchange rate, fees, delivery time and the exact INR amount your recipient receives.
- Confirm with your PIN and 2FA.
- Track the payout in real time and download the receipt for your records.
Option 2: API (for automated and bulk payouts)
Every endpoint below is in the Yativo API documentation. Production calls go to https://api.yativo.com/api/v1, and the sandbox runs at https://smtp.yativo.com/api/v1.
Authenticate every request with the X-Api-Key and X-Api-Secret headers. Each key only works from the server IPs listed on it. These API keys replaced bearer tokens, and login tokens stop working from servers on October 15, 2026, as covered in our October update. Every POST request also needs a unique Idempotency-Key header.
Step 1. Generate a USDC funding address on Solana to top up your USD balance:
POST https://api.yativo.com/api/v1/crypto/create-wallet
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
Idempotency-Key: a55e1057-0001-4a7b-9c0d-1e2f3a4b5c01
Content-Type: application/json

{
  "currency": "USDC_SOL"
}
Step 2. List the payout methods available for India:
curl "https://api.yativo.com/api/v1/payment-methods/payout?country=IND" \
  -H "X-Api-Key: $YATIVO_API_KEY" \
  -H "X-Api-Secret: $YATIVO_API_SECRET" \
  -H "Accept: application/json"
POBO (Local) is active and carries gateway ID 1057. Always read the ID from the live response instead of hardcoding it.
Step 3. Fetch the required fields for that gateway:
GET https://api.yativo.com/api/v1/beneficiary/form/show/1057
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
The response lists every required field and the accepted values for each one. Build your payment_data object from it. For field details, see API documentation.
Step 4. Create the beneficiary. Replace the placeholder with the fields the form returned:
POST https://api.yativo.com/api/v1/beneficiaries/payment-methods/
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
Idempotency-Key: a55e1057-0002-4b8c-0d1e-2f3a4b5c6d02
Content-Type: application/json

{
  "gateway_id": 1057,
  "nickname": "Pune Component Works Pvt Ltd",
  "currency": "INR",
  "customer_id": "e8caa491-57b6-4c39-9e3a-d2c97e47fbf0",
  "payment_data": {
    "{field_from_form}": "{value}"
  }
}
Step 5. Optionally, lock your rate. Quotes hold for 5 minutes:
POST https://api.yativo.com/api/v1/exchange-rate
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
Idempotency-Key: a55e1057-0003-4c9d-0e1f-2a3b4c5d6e03
Content-Type: application/json

{
  "from_currency": "USD",
  "to_currency": "INR",
  "method_id": 1057,
  "method_type": "payout",
  "amount": 5000
}
Step 6. Initiate the payout from your USD balance:
POST https://api.yativo.com/api/v1/wallet/payout
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
Idempotency-Key: a55e1057-0004-4d0e-1f2a-3b4c5d6e7f04
Content-Type: application/json

{
  "debit_wallet": "USD",
  "amount": 5000,
  "payment_method_id": 8101,
  "customer_id": "e8caa491-57b6-4c39-9e3a-d2c97e47fbf0",
  "quote_id": "4a72ecf8-6c8a-4e38-9971-8aabe9f785ed"
}
Use the id from the beneficiary response as payment_method_id. For bulk runs, repeat the call per beneficiary, as described on our payouts page.
Which India Payout Option Should You Use?
| POBO (Local) INR | SWIFT (USD) | SWIFT (POBO) INR | |
| Settlement speed | Next business day (T+1) | Next business day (T+1) | Next business day (T+1) |
| Required details | Name, IFSC, account (see API documentation) | See API documentation | See API documentation |
| Best for | Local INR bank credits with POBO labeling | Recipients who want USD | POBO-labeled INR via SWIFT path |
| Availability | Active (featured local) | Active | Active |
| Currency received | INR | USD | INR |
Best Practices for India Payouts
Plan for T+1, not same-day. India’s featured local rail is POBO. Build payroll and supplier calendars around next-business-day delivery.
Match the name to the account. Banks reject credits when the legal name does not match the account holder. Capture the name exactly as the bank shows it.
Validate the IFSC before you create the beneficiary. An 11-character IFSC that fails a simple format check will fail at payout time too.
Lock the rate on large payouts. Exchange-rate quotes hold for 5 minutes, so lock one for payroll runs and large invoices. You then know the exact rupee amount before you confirm.
Confirm the POBO endorsement early. Gateway 1057 needs pay-on-behalf-of setup. Get that cleared with your account executive before you promise the corridor to customers.
Frequently Asked Questions
Does my recipient in India need a crypto wallet?
No. Your recipient gets Indian rupees in their normal bank account. They never interact with stablecoins, and the payment arrives as a domestic credit.
Is it legal and compliant to pay Indian recipients this way?
Yes, when the payout runs through regulated infrastructure. Yativo is registered with FinCEN as a Money Services Business, registration number 31000270723339. A licensed local payout partner makes the domestic delivery, so your recipient sees a normal local payment. Your own tax and reporting duties still apply, so confirm them with your compliance advisor.
How long does an INR local bank transfer payout take?
India’s featured local method is POBO (Local), gateway ID 1057. It settles next business day (T+1), not under 30 minutes. SWIFT, gateway ID 618, and SWIFT (POBO), gateway ID 1112, also settle next business day (T+1). Your quote always shows the delivery time before you confirm.
Why is India T+1 instead of under 30 minutes?
The only active local INR method in Yativo’s catalog today is POBO (Local). POBO local rails settle next business day (T+1) by design. Do not expect same-day Instant-style settlement on this corridor until a non-POBO local bank method is enabled for your account.
What bank details do I need?
Collect the legal name that matches the account, the 11-character IFSC, and the account number. The dashboard form or GET /beneficiary/form/show/1057 lists every required field. For payment_data field names, see API documentation.
Can my recipient receive US dollars instead of rupees?
Not through POBO (Local), which delivers INR. For dollars, use SWIFT, gateway ID 618, which pays USD and settles next business day (T+1). Check GET /payment-methods/payout?country=IND for methods enabled on your account.
Start Paying Out in India in Rupees
India took in about US$135.46 billion in remittances in FY25, and UPI alone cleared roughly 185.9 billion transactions in FY2024-25. Yativo lets you fund in USDC or USD and deliver INR to local bank accounts through a licensed local payout partner. Settlement on the featured POBO local rail is next business day (T+1), and you get one API for every payout. Book a demo to set up your first India payout, or contact sales if you already know your corridor volume.
Sources
- The Economic Times: Diaspora remittances hit new record at $135.46 bn in FY25
- Reserve Bank of India: Annual Report 2024-25, Payment System Indicators
- Reserve Bank of India: Payment Systems in India publications
- World Bank: Personal remittances received, India
- World Bank: Remittance Prices Worldwide
- Yativo: Yativo API Documentation
- Yativo: Safer API access, three new virtual accounts and new payment links