
Your freight partner in Callao bills in dollars and banks in dollars. Yet your US$8,000 wire lands as US$7,940, two days late, after a correspondent bank took its cut.
Local bank transfer payouts to Peru with stablecoin settlement fix that. You fund in USDC or USD, and your recipient gets US dollars in their own Peruvian dollar account through a domestic transfer.
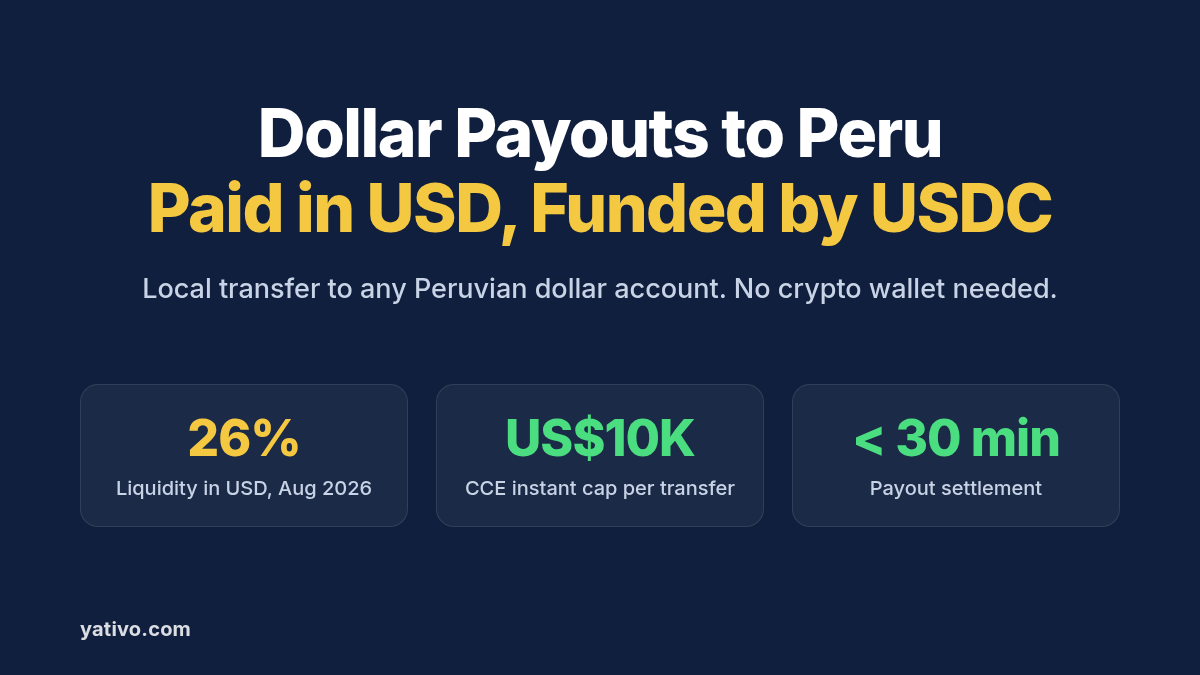
Dollars are part of everyday banking in Peru. About 26% of the banking system’s liquidity was held in dollars in August 2026, according to the Banco Central de Reserva del Perú (BCRP). Many suppliers, landlords and contractors keep a dollar account next to their soles account.
This guide covers why dollar payouts to Peru get expensive, how the stablecoin-funded flow works, and which details you need. It then walks through your first USD payout by dashboard and by API.
Why Paying Dollars into Peru Is Harder Than It Should Be
Peruvian banks handle dollars every day. The friction is the international leg, where your payment passes through correspondent banks before it reaches a local dollar account.
Small cross-border transfers are expensive. Sending small amounts abroad costs an average of 6.36% of the amount sent, according to the World Bank. On US$30,000 a month in supplier payments, that average would cost you US$1,908 every month. We break down more of these costs in the hidden costs of international payments.
Correspondent fees come out of the principal. An intermediary bank can deduct its fee before the wire arrives. Your supplier then chases a shortfall that nobody on your side approved.
Currency mismatches cost twice. A dollar wire sent to a soles account gets converted at the bank’s rate. Converting back to dollars later costs your recipient again.
Local rails have limits. CCE immediate transfers at Scotiabank Peru cap at US$10,000 per operation, while scheduled transfers sent after 2:30 p.m. arrive the next business day.
Local Bank Transfer Payouts to Peru with a Stablecoin Layer: How Dollar Payouts Work
Yativo is payment infrastructure, not a bank. We use stablecoins as the settlement layer between your balance and Peru. A licensed local payout partner then delivers the dollars on the ground.
- You fund your Yativo float balance with a fiat or stablecoin deposit, such as USDC.
- Yativo converts the payout value to USDC and settles it on-chain.
- A licensed local payout partner in Peru receives the stablecoin settlement.
- The partner converts USDC to US dollars and sends a domestic transfer to the recipient’s dollar CCI.
- Your recipient receives dollars in their normal Peruvian bank account.
Your recipient does not need a crypto wallet. They never see or touch stablecoins. On their side, the payment looks like any domestic dollar transfer from a local sender.
Because the last leg is domestic, no correspondent bank sits between you and your recipient. Peru’s interbank system is also busy, with 81.5 million CCE immediate transfers in August 2026, based on BCRP data. For more on the settlement layer, read how to receive international payments in stablecoins.
Supported Payout Rails for Peru in USD
Yativo’s active USD payout method for this guide is Bank Transfer (USD), which pays dollars into a Peruvian dollar account identified by its CCI. Our Peru list also includes SWIFT and a soles bank transfer.
Bank Transfer (USD)
Dollar transfers between Peruvian banks clear through the Cámara de Compensación Electrónica (CCE), the same system that moves soles. Immediate transfers are credited in real time and run 24/7, including holidays.
Required details: the fields returned by the Peru payout form for gateway ID 502. Expect the holder’s name and ID, the bank, the account type and the 20-digit CCI of a dollar account.
Settlement time: payouts via Bank Transfer (USD) settle in under 30 minutes.
Best for: importers’ suppliers, logistics partners, landlords and contractors who invoice in dollars.
Peru’s payout list also returns a second Bank Transfer entry in dollars, gateway ID 190. Use the ID enabled for your account, and ask your account executive if both appear.
Other options
If your recipient banks outside Peru, use SWIFT, gateway ID 688, which pays USD internationally. If they prefer soles, use Bank Transfer (PEN), covered in our guide to soles (PEN) payouts in Peru.
Recipient Details to Collect Before Your First USD Payout
The payout form for gateway 502 is the authoritative field list. Our API documentation does not publish that form yet, so read it from your dashboard or from the form endpoint shown below. Collect these details during onboarding so you can fill it without a round of emails.
- Holder type: individual or company.
- Legal name: full name as it appears on the DNI, or the registered company name.
- ID number: DNI or carnet de extranjería for individuals, or the 11-digit RUC for companies.
- Bank: for example Banco de Crédito del Perú, Interbank, BBVA or Scotiabank.
- Account type: savings or checking.
- Dollar CCI: the 20-digit interbank code of the dollar account, not the soles account.
- Contact details: email and phone, so the recipient can confirm receipt.
Ask for a screenshot of the dollar account details from the bank’s app during onboarding. It confirms the currency and removes most typing errors before the first payout.
How to Send a USD Payout to Peru via Yativo
Option 1: Dashboard (for manual payouts)
- Fund your Yativo float balance with either a fiat or a stablecoin deposit.
- Go to Transfer in your Yativo dashboard.
- Select the float wallet you are paying with, for example USD, EUR, MXN or whichever balance you funded.
- Choose the customer you are paying on behalf of. This step is necessary for fintechs that run payouts on behalf of their customers.
- Choose Peru as the destination country and the Bank Transfer (USD) payout method.
- Enter the recipient details the payout form asks for, such as the holder’s name, DNI or RUC, bank, account type and the 20-digit CCI of the dollar account.
- Enter the amount in USD.
- Review the quote: fees, delivery time and the exact USD amount your recipient receives.
- Confirm with your PIN and 2FA.
- Track the payout in real time and download the receipt for your records.
Option 2: API (for automated and bulk payouts)
Every endpoint below is in the Yativo API documentation. Production calls go to https://api.yativo.com/api/v1, and the sandbox runs at https://smtp.yativo.com/api/v1.
Authenticate every request with the X-Api-Key and X-Api-Secret headers. Each key only works from the server IPs listed on it. These API keys replaced bearer tokens, and login tokens stop working from servers on October 15, 2026, as covered in our October update. Every POST request also needs a unique Idempotency-Key header.
Step 1. Generate a USDC funding address on Solana to top up your USD balance:
POST https://api.yativo.com/api/v1/crypto/create-wallet
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
Idempotency-Key: 8c9d0e1f-2a3b-4c4d-9e5f-6a7b8c9d0e01
Content-Type: application/json

{
  "currency": "USDC_SOL"
}
Step 2. List the payout methods available for Peru:
curl "https://api.yativo.com/api/v1/payment-methods/payout?country=PER" \
  -H "X-Api-Key: $YATIVO_API_KEY" \
  -H "X-Api-Secret: $YATIVO_API_SECRET" \
  -H "Accept: application/json"
Bank Transfer (USD) is active and carries gateway ID 502. Always read the ID from the live response instead of hardcoding it.
Step 3. Fetch the required fields for that gateway:
GET https://api.yativo.com/api/v1/beneficiary/form/show/502
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
The response lists every required field and the accepted values for each one. Build your payment_data object from it. For field details, see API documentation.
Step 4. Create the beneficiary. Replace the placeholder with the fields the form returned:
POST https://api.yativo.com/api/v1/beneficiaries/payment-methods/
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
Idempotency-Key: 4c5d6e7f-8a9b-4c0d-8e1f-2a3b4c5d6e01
Content-Type: application/json

{
  "gateway_id": 502,
  "nickname": "Andes Logística SAC",
  "currency": "USD",
  "customer_id": "e8caa491-57b6-4c39-9e3a-d2c97e47fbf0",
  "payment_data": {
    "{field_from_form}": "{value}"
  }
}
Step 5. Initiate the payout from your USD balance:
POST https://api.yativo.com/api/v1/wallet/payout
X-Api-Key: $YATIVO_API_KEY
X-Api-Secret: $YATIVO_API_SECRET
Idempotency-Key: 6f7a8b9c-0d1e-4f2a-9b3c-4d5e6f7a8b01
Content-Type: application/json

{
  "debit_wallet": "USD",
  "amount": 5000,
  "payment_method_id": 6377,
  "customer_id": "e8caa491-57b6-4c39-9e3a-d2c97e47fbf0"
}
Use the id from the beneficiary response as payment_method_id. Your dashboard quote shows fees and the exact dollar amount before you confirm. For bulk runs, repeat the call per beneficiary, as described on our payouts page.
Which Peru Payout Option Should You Use?
| Bank transfer (USD) | Bank transfer (PEN) | USD via SWIFT | |
| Settlement speed | Under 30 minutes | Under 30 minutes | Depends on correspondent banks |
| Required details | Name, ID, bank, dollar CCI (see API documentation) | Name, ID, bank, account type, CCI, purpose | See API documentation |
| Best for | Recipients with a dollar account in Peru | Suppliers, contractors, payroll in soles | Recipients banking abroad |
| Availability | Active | Active | Active |
| Currency received | USD | PEN | USD |
Best Practices for Dollar Payouts to Peru
Confirm the account currency first. Each Peruvian account has its own CCI, and a dollar account’s CCI differs from the soles one. Ask which CCI belongs to the dollar account before the first payout.
Match the ID to the account holder. Make sure the DNI or RUC belongs to the person or company that owns the account. Mismatches are a common reason for returns.
Agree on the invoice currency. Decide with each supplier whether you pay in USD or PEN, and record it in your vendor file. Switching later means new beneficiary details.
Split very large invoices only if needed. Immediate dollar transfers carry per-operation caps at many Peruvian banks. Ask your account executive about limits before you schedule a large payment.
Stop hardcoding retired gateway IDs. The CCE method, gateway 1346, was sunset on September 2, 2026. Read gateway IDs from the payout methods endpoint at runtime instead.
Run one playbook across LATAM. The same flow works in other markets. See our guide to local payouts to Argentina via bank transfer and our breakdown of LATAM payout rails.
Frequently Asked Questions
Does my recipient in Peru need a crypto wallet?
No. Your recipient gets US dollars in their normal Peruvian bank account. They never interact with stablecoins, and the payment arrives as a domestic transfer.
Is it legal and compliant to pay Peruvian recipients in dollars this way?
Yes, when the payout runs through regulated infrastructure. Yativo is registered with FinCEN as a Money Services Business, registration number 31000270723339. A licensed local payout partner makes the domestic transfer, and dollar accounts are a normal part of Peruvian banking. Your own tax and reporting duties still apply, so confirm them with your compliance advisor.
How long does a USD payout to Peru take?
Payouts via Yativo settle in under 30 minutes. On the local side, CCE immediate transfers in dollars run 24/7, with a US$10,000 cap per operation at banks such as Scotiabank Peru.
Why would I pay dollars locally instead of sending a SWIFT wire?
A local dollar transfer moves between two Peruvian accounts, so it skips correspondent banks and their deductions. A SWIFT wire is still useful when your recipient banks outside Peru.
What happens if I send dollars to a soles CCI?
The receiving bank may convert the dollars at its own rate, or reject the transfer. Always confirm that the CCI belongs to a dollar account before you pay.
Can my recipient receive soles instead?
Yes. Yativo pays soles (PEN) into any Peruvian CCI through Bank Transfer (PEN), which we cover in our guide to soles (PEN) payouts in Peru.
Start Paying Dollars into Peru Without the Wire
With about a quarter of Peru’s bank liquidity in dollars, many of your Peruvian partners already want to be paid in USD. Yativo lets you fund in USDC or USD and deliver dollars to Peruvian dollar accounts through a licensed local payout partner. Your recipients get a domestic transfer in under 30 minutes, with no correspondent bank in between. Book a demo to set up your first USD payout to Peru.
Sources
- Banco Central de Reserva del Perú: Coeficiente de Dolarización de la Liquidez (%) (monthly series)
- Banco Central de Reserva del Perú: CCE: Transferencias inmediatas, número total (monthly series)
- Scotiabank Perú: Transferencia Interbancaria vía CCE
- World Bank: Remittance Prices Worldwide
- Yativo: Yativo API Documentation
- Yativo: Safer API access, three new virtual accounts and new payment links
- Yativo: Important Update: Streamlining Our Rail Network Effective September 2, 2026